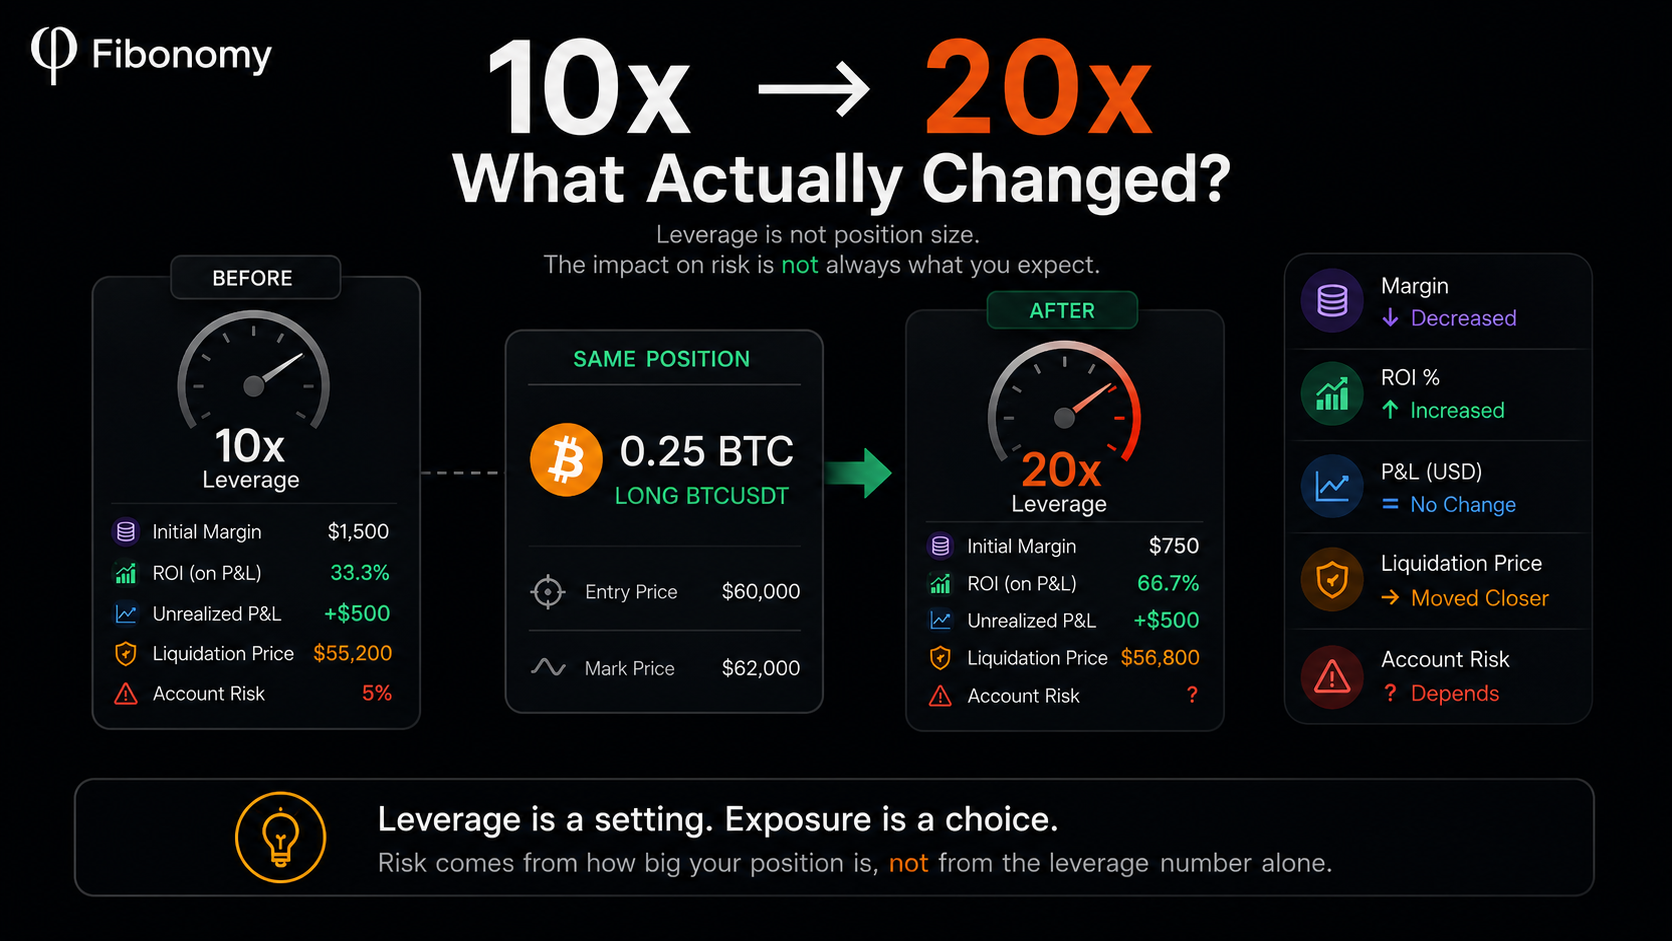
You are LONG BTCUSDT.
Your position is already open.
You change:
10x
→
20x
The number beside the position doubled.
So did your risk double?
Not necessarily.
This is one of the most misunderstood parts of futures trading.
Changing leverage in futures can change how much margin the exchange requires to support a position without changing the position itself.
If your:
- position size stays the same,
- entry price stays the same,
- and market price stays the same,
then simply changing the leverage setting does not automatically double your actual P&L.
What changed may be the margin behind the position, not the market exposure of the position.
That distinction changes how you should read leverage entirely.
Quick Answer
For an already-open futures position, separate these two things:
LEVERAGE

vs

POSITION SIZE
If the position stays:
0.25 BTC LONGchanging:
10x
→
20x
does not magically turn it into:
0.50 BTC LONGThe position is still 0.25 BTC.
Changing leverage in futures does not automatically change position size or dollar P&L.
Therefore, the P&L effect of the next $1,000 BTC move is still approximately:
0.25 BTC × $1,000

=

$250
at 10x or 20x.
What can change instead:
Initial Margin

Available Margin

ROI %

Liquidation Buffer

Liquidation Price

Account Margin State
The exact result depends on:
- Cross vs Isolated Margin,
- the exchange,
- the contract,
- maintenance-margin tiers,
- and what happens to the released or required margin.
Bybit’s current P&L documentation explicitly states that leverage does not change the actual unrealized P&L of a fixed-size position; it changes the Initial Margin used in the calculation.
Table of Contents
Leverage Is Not Position Size
This is the first mental model to fix.
Suppose:
Account Equity:
$10,000

BTC Entry:
$60,000

Position:
0.25 BTC
Position notional:
0.25 × $60,000

=

$15,000
Now compare three leverage settings.
5x
Simplified Initial Margin:
$15,000 ÷ 5

=

$3,000
10x
$15,000 ÷ 10

=

$1,500
20x
$15,000 ÷ 20

=

$750
What changed?
Initial Margin:

$3,000
→
$1,500
→
$750
What did not change?
Position Size:

0.25 BTC

Position Notional:

$15,000
That is the key.
Bybit describes the same relationship: higher leverage lowers the Initial Margin Rate while the quantity of a fixed position remains unchanged.
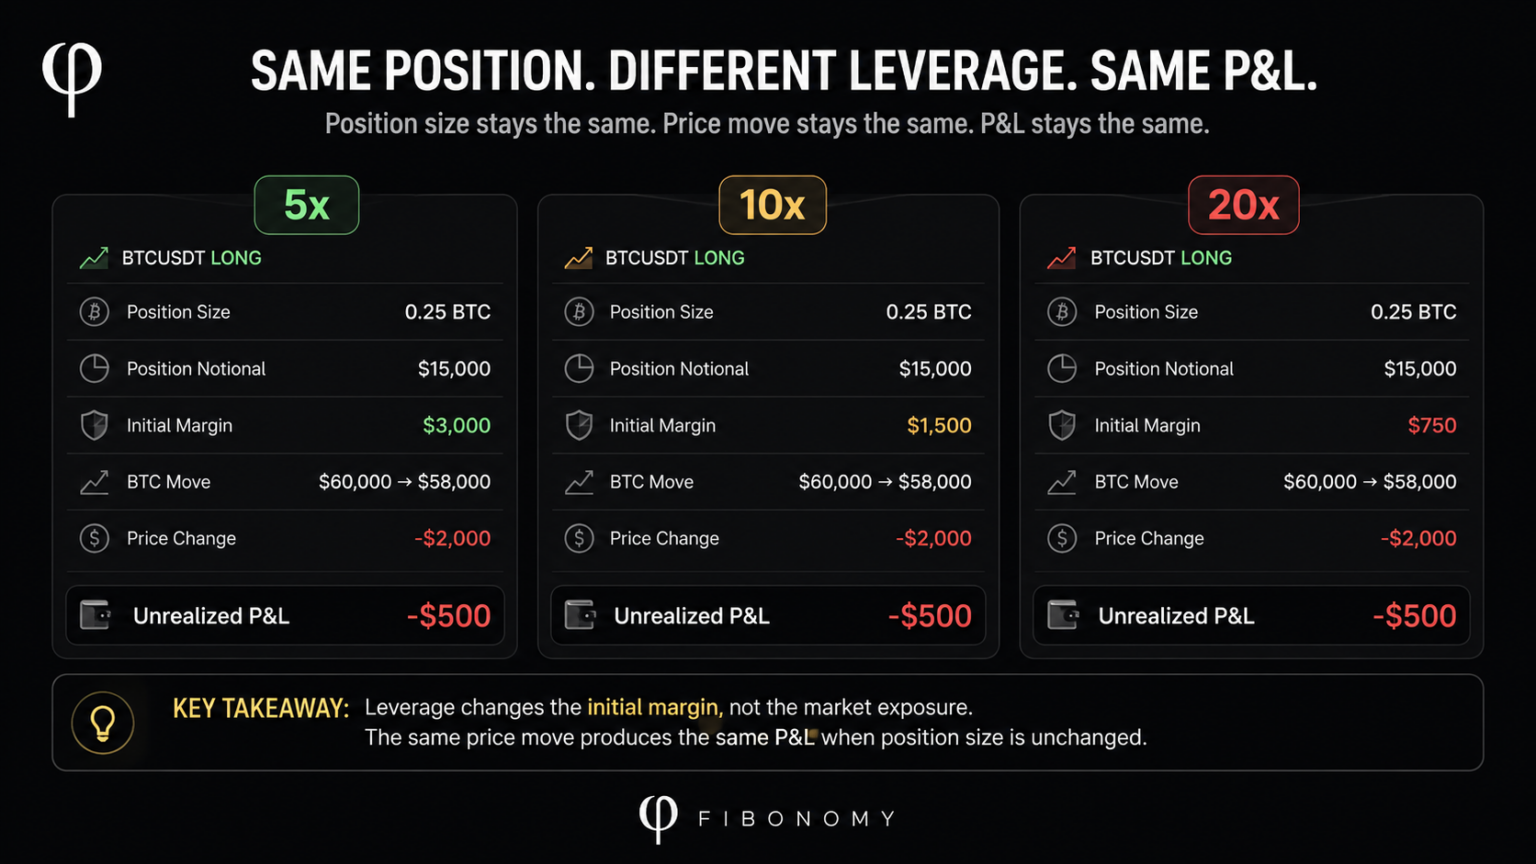
The Same Price Move Produces the Same P&L
Now BTC moves:
$60,000
→
$58,000
Difference:
-$2,000For a 0.25 BTC long:
0.25 × -$2,000

=

-$500
At 5x:
-$500At 10x:
-$500At 20x:
-$500Why?
Because the P&L is being created by:
Position Size
×
Price Movement
not by:
Leverage Number
×
P&L
Bybit’s current documentation says actual P&L is determined by position quantity and price movement; leverage alone does not increase absolute P&L.
What Changing Leverage in Futures Actually Changes
Because something else changed.
The position is now supported by less Initial Margin.
Using the same example:
Position Notional:
$15,000
At 5x:
Initial Margin:
≈ $3,000
At 20x:
Initial Margin:
≈ $750
Same market exposure.
Less margin allocated to support it.
Conceptually:
Same Position
+
Less Margin Buffer
=
Liquidation Can Become More Sensitive
But even this needs a qualification:
Exactly how liquidation changes after adjusting leverage is exchange- and margin-mode-specific.
There is no universal rule that every futures platform handles an already-open position the same way.
ROI Can Double While Your Actual P&L Does Not
This is probably the most visually misleading effect.
Suppose:
Unrealized P&L:
+$500
At 10x:
Initial Margin:
$1,500

ROI:

$500 ÷ $1,500

≈ 33.3%
At 20x:
Initial Margin:
$750

ROI:

$500 ÷ $750

≈ 66.7%
The screen can now show:
ROI

33.3%
→
66.7%
It looks like the trade became twice as profitable.
It didn’t.
Actual unrealized P&L is still:
+$500Only the denominator changed.
Bybit explicitly documents this effect: increasing leverage can increase displayed ROI because Initial Margin falls, while the actual P&L remains unchanged.
So:
Higher ROI %
≠
More Dollar Profit
This is exactly the type of interface number that needs context before interpretation.
Your Risk to a Stop Can Stay Exactly the Same
Now suppose the position has:
Entry:
$60,000

Position:
0.25 BTC

Stop:
$58,000
Potential loss to the stop:
($60,000 − $58,000)
×
0.25 BTC

=

$500
Account equity:
$10,000Capital at risk:
$500
÷
$10,000

=

5%
Now change:
5x
→
10x
→
20x
If these remain unchanged:
Position Size:
0.25 BTC

Stop:
$58,000

Account Equity:
$10,000
then the approximate stop-based potential loss is still:
$500and account risk is still:
5%ignoring execution slippage and fees.
That gives us another important distinction:
Changing leverage does not automatically change the amount you lose at your planned stop if exposure and stop location remain unchanged.
But it may change how much room exists between the position and exchange liquidation.
Those are different risk concepts.
To see why position size and stop distance matter more than the leverage label when measuring planned account risk, read How Much of Your Account Is Actually at Risk Across Open Futures Positions?
Stop Risk and Liquidation Risk Are Not the Same
Imagine:
Capital Risk to Stop:
5%
That tells you:
“Approximately how much account equity is exposed if the stop executes where planned?”
Liquidation risk asks another question:
“Can the exchange force-close this position before or around that scenario because available margin is insufficient?”
So:
STOP-BASED RISK

Position Size
×
Distance to Stop
is different from:
LIQUIDATION RISK

Margin
+
Maintenance Requirement
+
Account State
+
Mark Price
Changing leverage can leave the first almost unchanged while changing the second.
If you want to see why a stop loss and the exchange’s liquidation boundary can still behave differently, read Why You Can Be Liquidated With a Stop Loss.
That is why a single leverage number cannot describe the full risk of the trade.
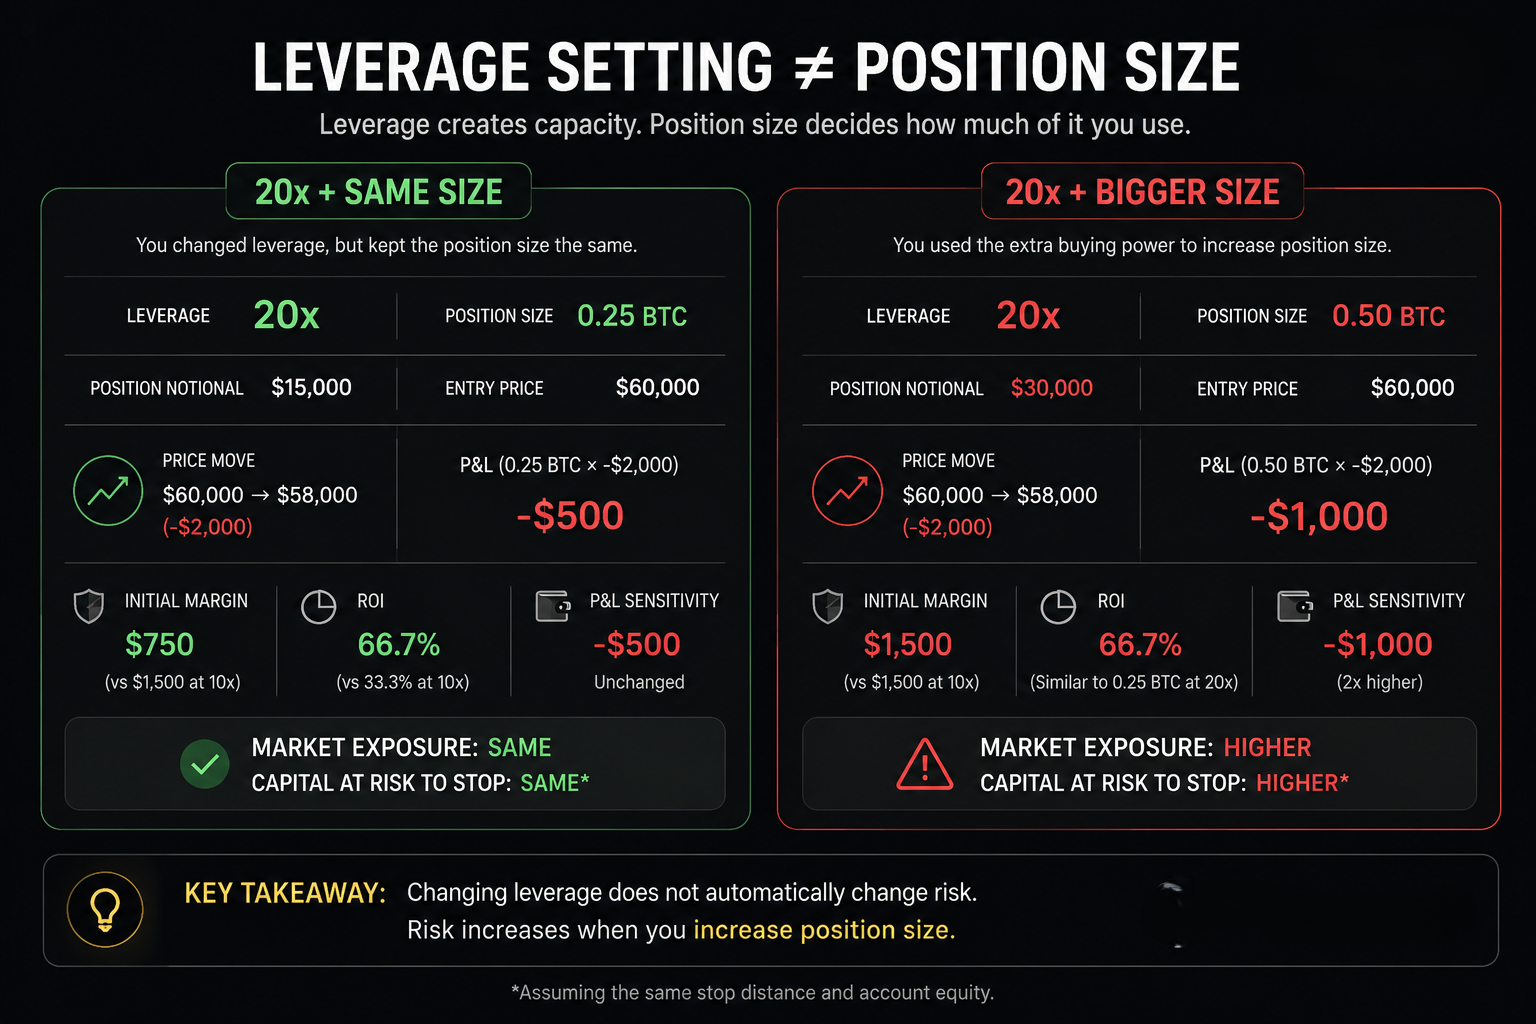
Where Leverage Actually Becomes Dangerous: Using It to Increase Size
Now change the scenario.
You have:
$2,000available for the trade.
At 10x, you open:
$20,000 positionAt 20x, instead of opening the same $20,000 position, you use the extra buying power and open:
$40,000 positionNow leverage has indirectly changed exposure.
Suppose both positions use a stop 2% away.
$20,000 Position
Potential loss:
$20,000 × 2%

=

$400
$40,000 Position
Potential loss:
$40,000 × 2%

=

$800
The risk doubled.
But the correct causal chain is:
Higher Leverage
        ↓
Allowed Larger Position
        ↓
Trader Increased Position Size
        ↓
Market Exposure Doubled
        ↓
Potential Loss Doubled
Not:
20x
automatically
=
2× loss
This distinction matters enormously.
Leverage creates capacity. Position size decides how much of that capacity you actually use.
Higher Leverage Can Move Liquidation Closer
Although leverage alone does not change fixed-position P&L, it can affect liquidation mechanics.
For example, OKX’s current futures documentation states that increasing leverage on an open position reduces the margin required to sustain it; its derivatives guidance also notes that higher leverage can move the liquidation price closer to entry.
Bybit’s isolated-margin liquidation formulas explicitly include leverage because leverage affects Initial Margin.
So a simplified relationship can be:
Leverage ↑

Initial Margin ↓

Liquidation Buffer ↓

Liquidation Price
can move closer
But do not turn that into a universal formula.
Because another exchange may treat the same adjustment differently.
The liquidation price itself can also change as the account around the position changes. See Why Does My Liquidation Price Keep Changing in Cross Margin?.
Exchange Rules Matter More Than the Label
This is where generic advice such as:
“Increasing leverage always moves liquidation closer.”
becomes too broad.
OKX
OKX states that increasing leverage on an open position reduces the margin required, while decreasing leverage requires additional funds to cover the higher margin requirement.
Its current educational documentation says increasing leverage can bring liquidation price closer to entry.
Bybit
Bybit states that adjusting leverage changes Initial Margin while position quantity remains unchanged.
It also explicitly says leverage changes ROI%, not the actual unrealized P&L of the fixed-size position.
Its isolated liquidation formulas include leverage as part of Initial Margin.
CoinEx
CoinEx demonstrates why we should not universalize exchange behavior.
Its current USDⓈ-margined documentation says that in Cross Margin, adjusting leverage causes allocated cross margin to be recalculated and may change both risk ratio and liquidation price.
But in Isolated Margin it currently states:
- increasing leverage does not change liquidation price,
- decreasing leverage triggers a recalculation of required margin and may change liquidation price.
Same action:
Change LeverageDifferent implementation.
That is exactly why Fibonomy should reconstruct what the exchange actually did rather than infer account risk from the leverage label alone.
Binance Futures Adds Another Layer: Position Tiers
Binance Futures also ties leverage and Maintenance Margin to exposure tiers.
Current Binance documentation shows leverage/margin brackets where larger notional positions have different maximum leverage and Maintenance Margin Rates. Recent 2026 updates continue to change these tiers for individual USDⓈ-M perpetual contracts.
Binance also describes liquidation risk using Margin Ratio:
Maintenance Margin
÷
Margin Balance
with liquidation risk reaching the critical threshold when Margin Ratio reaches 100%.
This creates another distinction:
Selected Leverageis not the whole account risk model.
You also need:
Position Notional

Maintenance Margin Tier

Margin Balance

Mark Price

Other Positions
Cross Margin Makes the Leverage Number Even Less Informative
In Isolated Margin:
Position
↓
Allocated Margin
Changing leverage can directly change the margin structure surrounding that position.
Cross Margin is different.
           ACCOUNT
              │
       Shared Margin Pool
              │
      ┌───────┼───────┐
      BTC     ETH     SOL
Now suppose BTC is still:
0.25 BTCbut you increase its selected leverage.
The position quantity may remain unchanged. In Cross Margin, changing leverage in futures can also change how margin is allocated across the account without changing the position quantity itself.
However, the margin reserved for that position can change, potentially affecting:
Available Balance

Other Positions

Account Margin Ratio

Liquidation Buffer
CoinEx explicitly says its Cross Margin system recalculates allocated cross margin when leverage changes.
On account-level systems, the relevant question becomes:
Where did the released or newly required margin go inside the account?
Not simply:
“What leverage number is displayed?”
In Cross Margin, the leverage setting is only one part of the account state. Other positions, unrealized P&L, maintenance requirements, funding, and available margin can all affect the same liquidation process. We break down that account-level mechanism in What Actually Triggers Liquidation in Cross Margin?
Effective Leverage Can Be Different From Selected Leverage
Another useful distinction:
You might select:
20xbut that does not necessarily mean the entire account is economically operating at exactly 20x.
Consider:
Account Equity:
$10,000

Total Futures Exposure:
$20,000
A simplified account-level effective leverage is around:
$20,000
÷
$10,000

=

2x
Now imagine one position’s interface says:
20xThe selected leverage on that position and the effective leverage of the whole account are describing different things.
Bybit similarly distinguishes effective leverage in Cross Margin from the leverage selector and relates effective leverage to position value versus available supporting resources.
That means:
Displayed Leverage
≠
Complete Account Exposure
One Leverage Change Can Change Four Numbers but Not the Trade
Suppose:
BTCUSDT LONG

Size:
0.25 BTC

Entry:
$60,000

Market:
$62,000

Unrealized P&L:
+$500
At 10x:
Initial Margin:
≈ $1,500

ROI:
≈ 33.3%
Change leverage to 20x.
Now you may see:
Leverage:
10x → 20x

Initial Margin:
$1,500 → $750

ROI:
33.3% → 66.7%

Liquidation State:
Changed
But:
Position Size:
0.25 BTC → 0.25 BTC

Unrealized P&L:
+$500 → +$500
Four interface numbers may move.
The market position itself did not become larger.
That is precisely why reading raw exchange fields independently can create the wrong story.
When Does Changing Leverage Actually Change Capital Risk?
Changing the leverage selector itself may not change your stop-based capital risk.
But leverage can indirectly change risk when you use the newly available margin.
For example:
20x selected

↓

$750 margin released

↓

Trader opens ETHUSDT

↓

Total account exposure ↑

↓

Total capital risk ↑
Or:
20x selected

↓

Trader sizes BTC up

↓

Position size ↑

↓

Potential loss to stop ↑
Now the risk genuinely changed.
The event that mattered was not simply:
LEVERAGE CHANGEDIt was what happened after or because of the leverage change.
Why This Matters After You Add to a Position
This connects directly to the previous article.
You may:
Change leverage
+
Add to position
within a few seconds.
The screen then shows:
Leverage changed

Average entry changed

Position size changed

Liquidation price changed

Margin changed
If you treat all of that as one event, you cannot know what caused what.
Instead reconstruct the chain:
10x → 20x
      ↓
Initial margin changed

Then

+0.10 BTC
      ↓
Position size changed
      ↓
Average entry changed
      ↓
Potential loss changed
      ↓
Maintenance requirement changed
We covered the second part separately in:
What Happens to Liquidation Risk When You Add to a Futures Position?
That separation is critical.
What Should You Recalculate After Changing Leverage?
Do not stop at:
10x → 20xCheck these.
1. Position Size
Did quantity actually change?
If not, market exposure may still be identical.
2. Initial Margin
How much margin is now assigned or required?
3. Unrealized P&L
Did the dollar P&L actually change?
If only ROI% changed, do not confuse the two.
4. ROI %
Did the percentage change simply because Initial Margin changed?
5. Stop-Based Capital Risk
Recalculate:
Position Size
×
Distance to Stop
If neither changed, leverage alone may not have changed this number.
6. Liquidation Price
Did the exchange recalculate it?
7. Available Balance
Was margin released or newly required?
8. Other Positions
In Cross Margin, did the change alter resources available to the rest of the account?
9. Maintenance Margin Tier
Is your position still in the same tier?
10. What Happened Next?
Did you use the released margin to:
- add to BTC,
- open ETH,
- open SOL,
- or place another order?
That may be the event that actually increased account risk.
The Better Question
Instead of asking:
“Is 20x twice as risky as 10x?”
ask:
“What exactly changed when I moved from 10x to 20x?”
Then inspect:
Position Size
Changed?

        ↓

Initial Margin
Changed?

        ↓

P&L
Changed?

        ↓

ROI%
Changed?

        ↓

Liquidation State
Changed?

        ↓

Available Margin
Changed?

        ↓

Did I use that margin
to increase exposure?
Now you can distinguish:
A DISPLAY CHANGEfrom:
A POSITION CHANGEand:
AN ACCOUNT-RISK CHANGEThose are not always the same event.
The Bottom Line
Changing leverage in futures should be evaluated by what happened to margin, liquidation conditions, and actual exposure—not by the leverage number alone. Leverage is powerful.
But the leverage number by itself is a poor description of how much account capital is actually at risk.
For a fixed position:
10x → 20xcan change:
- Initial Margin,
- ROI%,
- available margin,
- liquidation conditions,
while leaving:
- position size,
- market exposure,
- and actual P&L sensitivity
unchanged.
Risk increases materially when higher leverage is used to create more exposure, when it reduces the liquidation buffer, or when released margin is used to add additional account risk.
So instead of asking:
“How much leverage am I using?”
ask:
“How large is the position, how much capital can it lose, what supports it, and what actually changed after I adjusted leverage?”
That is the account truth hidden behind the 20x label.
See What Actually Changed
Fibonomy separates position changes from account changes so you can see whether leverage changed the margin, exposure, liquidation state, or actual capital at risk—and what happened next.
Not a signal. Perpetual futures can produce rapid losses and liquidation. Exchange leverage, margin and liquidation rules vary by product and account mode.
Sources
Bybit — FAQ: P&L Calculation
Current explanation that leverage changes Initial Margin and ROI%, but does not change actual P&L for a fixed-size position.
Bybit — Does Leverage Affect Your Unrealized P&L?
Position quantity, Initial Margin Rate and the difference between leverage and market exposure.
Bybit — Liquidation Price Calculation under Isolated Mode
How leverage, Initial Margin, Maintenance Margin and extra margin enter liquidation calculations.
OKX — Futures Margin Calculation Rules
Initial Margin, Cross/Isolated Margin and how adjusting leverage changes required margin.
OKX — What Is Leverage in Crypto Derivatives Trading?
Current explanation of leverage adjustments and liquidation-price effects on open positions.
CoinEx — Leverage and Margin Explanation for USDⓈ-Margined Contracts
Cross- and Isolated-Margin-specific behavior when leverage is adjusted.
Binance Futures — How to Reduce Your Chances of Getting Liquidated
Margin Ratio, Maintenance Margin, Margin Balance and the relationship between exposure and liquidation.
Binance Futures — Update on the Collateral Ratio and Leverage & Margin Tiers of USDⓈ-M Perpetual Contracts
Recent evidence that maximum leverage and Maintenance Margin rates depend on notional tiers and can change by contract.